
The article explains how liability limits, vehicle value, deductibles, and financial responsibilities help drivers determine the right amount of auto insurance coverage.
KEY HIGHLIGHTS
- State minimum coverage limits provide a legal starting point but may not offer sufficient financial protection after a serious accident.
- Liability insurance, collision coverage, and comprehensive coverage serve different purposes and should be evaluated based on individual needs.
- Vehicle value, deductible amounts, and financial circumstances can influence how much auto insurance coverage a driver needs.
- Uninsured and underinsured motorist coverage may provide additional protection when another driver lacks adequate insurance.
- Reviewing auto insurance policies after major life changes helps drivers maintain coverage that reflects their current circumstances.
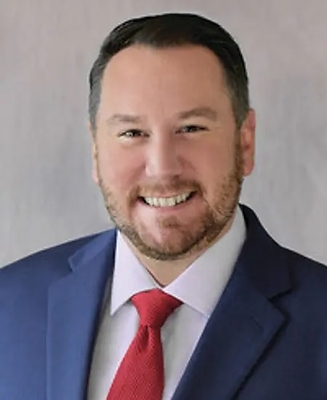
LIMA, Ohio, Nov. 13, 2026 /PRNewswire/ — How much auto insurance coverage do drivers really need? A HelloNation article answers this question with insights from Corey Frazer, an insurance expert in Lima, Ohio, and explains why choosing the right coverage involves more than meeting state insurance requirements.
Why Are State Minimum Auto Insurance Limits Not Always Enough?
The HelloNation article explains that every state establishes its own auto insurance requirements, although some states permit alternatives to traditional insurance. These requirements generally include liability insurance, which helps cover injuries or property damage a driver causes to others.
However, state minimum coverage limits are a legal baseline, not a complete assessment of financial risk. A serious accident can result in significant medical expenses, lost income, and vehicle repair costs that exceed minimum policy limits.
Corey Frazer, an insurance expert in Lima, Ohio, is featured as a source of insights on why drivers should consider their financial responsibilities when selecting liability coverage. If accident costs exceed the policy limits, the driver may be personally responsible for the remaining expenses.
The article emphasizes that understanding potential financial exposure is an important part of determining how much auto insurance coverage is appropriate.
How Does Liability Insurance Protect Drivers Financially?
The HelloNation article identifies liability insurance as one of the most important components of an auto insurance policy. Liability protection generally includes bodily injury liability and property damage liability, which address different types of expenses resulting from an at-fault accident.
Bodily injury liability helps cover injuries others suffer when the insured driver is responsible for a collision. Property damage liability helps pay for damage to another person’s vehicle or other property.
The amount of liability insurance a driver needs depends partly on financial circumstances and the potential costs of a serious claim. Medical treatment, lost wages, and property repairs can create substantial financial obligations.
According to the HelloNation article, drivers should evaluate whether their liability limits could reasonably address the consequences of a major accident rather than selecting coverage based solely on the lowest available premium.
When Do Collision and Comprehensive Coverage Make Sense?
The HelloNation article explains that vehicle value plays an important role in deciding whether to maintain collision coverage and comprehensive coverage.
Collision coverage generally helps pay for damage to the insured vehicle following an accident, subject to policy terms and deductibles. Comprehensive coverage typically applies to certain non-collision events, including theft, vandalism, hail, and storm-related damage.
Corey Frazer, an insurance expert in Lima, Ohio, explains why drivers with newer or more valuable vehicles may benefit from maintaining these protections. For older vehicles with lower market values, however, the cost of collision and comprehensive coverage may outweigh the potential financial benefit.
The article recommends comparing a vehicle’s current value with annual insurance premiums and deductible amounts. This comparison can help drivers determine whether maintaining physical damage coverage makes financial sense.
Drivers with financed or leased vehicles should also understand any insurance requirements established by their lenders or leasing companies.
How Do Deductibles Affect Auto Insurance Costs?
The HelloNation article explains that deductibles influence both insurance premiums and the amount a driver may need to pay after a covered claim.
A deductible is the amount a policyholder generally pays toward a covered loss before insurance contributes. Choosing a higher deductible can lower premiums, but it also increases the driver’s out-of-pocket responsibility when a claim occurs.
A lower deductible may reduce the immediate financial burden of vehicle repairs, although it generally results in higher insurance premiums.
The article emphasizes that drivers should consider how much they could comfortably afford to pay following an unexpected accident or covered loss. Selecting a deductible involves balancing monthly or annual insurance costs with financial readiness for an emergency.
Why Should Drivers Consider Uninsured and Underinsured Motorist Coverage?
The HelloNation article identifies uninsured and underinsured motorist coverage as another important consideration when evaluating auto insurance protection.
Depending on state requirements and policy terms, uninsured motorist coverage may provide financial protection when an at-fault driver has no applicable insurance. Underinsured motorist coverage may help when the responsible driver’s liability limits are insufficient to cover qualifying losses.
Some states require these protections, while others make them optional. The article encourages drivers to understand how uninsured and underinsured motorist coverage works in their policies and what types of losses it may cover.
This additional protection can be especially important when another driver’s insurance can’t cover the financial consequences of an accident.
When Should Drivers Review Their Auto Insurance Coverage?
The HelloNation article explains that auto insurance needs can change as a driver’s personal and financial circumstances evolve.
Buying a new vehicle, adding another household driver, or paying off an auto loan may affect the right coverage choices. Changes in income, savings, and other financial responsibilities can also affect how much liability protection you need.
Corey Frazer, an insurance expert in Lima, Ohio, is featured in the article as a source of guidance on evaluating auto insurance coverage based on current circumstances rather than relying on limits selected years earlier.
The article emphasizes that regular policy reviews can help drivers spot gaps in protection, reconsider deductibles, and determine whether existing coverage still fits.
Ultimately, choosing the right amount of auto insurance coverage requires balancing financial risk, vehicle value, policy limits, deductibles, and premium costs. Rather than relying exclusively on state minimum coverage limits, drivers benefit from understanding how different types of insurance work together to provide financial protection.
How Much Auto Insurance Coverage Do You Really Need? Features insights from Corey Frazer, insurance expert in Lima, Ohio, in HelloNation.
FREQUENTLY ASKED QUESTIONS
How Much Auto Insurance Coverage Do I Really Need?
According to Corey Frazer, insurance expert in Lima, Ohio, the HelloNation article explains that appropriate auto insurance coverage depends on a driver’s financial responsibilities, vehicle value, deductible preferences, and potential liability exposure. State minimum requirements provide a starting point, but you may need additional coverage to cover the costs of a serious accident.
Are State Minimum Auto Insurance Limits Enough?
Corey Frazer, an insurance expert in Lima, Ohio, explains in a HelloNation article that state minimum coverage limits may not provide adequate protection after a major collision. Medical expenses, lost income, and property damage can exceed minimum liability limits, potentially leaving the driver personally responsible for additional costs.
What Is the Difference Between Liability, Collision, and Comprehensive Coverage?
According to insights from Corey Frazer, an insurance expert in Lima, Ohio, liability insurance generally helps cover injuries or property damage caused to others. Collision coverage helps pay for damage to the insured vehicle following an accident, while comprehensive coverage generally addresses certain noncollision losses, such as theft, vandalism, and weather damage.
Should Drivers Choose a Higher or Lower Auto Insurance Deductible?
Corey Frazer, an insurance expert in Lima, Ohio, explains in a HelloNation article that higher deductibles can reduce insurance premiums but increase out-of-pocket expenses after a covered claim. Lower deductibles generally mean higher premiums while reducing what a driver must pay toward covered repairs. The appropriate choice depends on the driver’s financial situation and ability to handle unexpected expenses.
Why Is Uninsured and Underinsured Motorist Coverage Important?
Based on insights from Corey Frazer, Insurance Expert of Lima, Ohio, the HelloNation article explains that uninsured and underinsured motorist coverage may help protect drivers when an at-fault motorist has no insurance or insufficient liability coverage. The availability and scope of these protections depend on state requirements and policy terms.
When Should I Review or Change My Auto Insurance Coverage?
According to Corey Frazer, an insurance expert in Lima, Ohio, the HelloNation article recommends reviewing coverage after major changes, such as purchasing a vehicle, adding a household driver, paying off an auto loan, or changes in income and financial responsibilities. Regular reviews help ensure policy limits and coverage choices remain aligned with current needs.
About HelloNation
HelloNation is America’s Good News Network, a premier media platform built on the idea that good news travels faster when real people tell real stories. Through its community-focused publications and innovative “edvertising” approach, HelloNation delivers content that informs, inspires, and spotlights the leaders making a meaningful impact in their communities.
 View original content to download multimedia:https://www.prnewswire.com/news-releases/insurance-expert-corey-frazer-explains-how-much-auto-insurance-coverage-drivers-really-need-in-hellonation-302939015.html
SOURCE HelloNation
