
PASADENA, Calif., Oct. 26, 2026 /PRNewswire/ — Alexandria Real Estate Equities, Inc. (NYSE: ARE) announced financial and operating results for the third quarter ended September 30, 2026.
|
KEY HIGHLIGHTS |
||||||||
|
Operating results |
3Q26 |
3Q25 |
YTD 3Q26 |
YTD 3Q25 |
||||
|
Net loss attributable to Alexandria’s common stockholders – diluted: |
||||||||
|
In millions |
$ (638.5) |
(1) |
$ (234.9) |
$ (351.4) |
$ (356.1) |
|||
|
Per share |
$ (3.74) |
$ (1.38) |
$ (2.06) |
$ (2.09) |
||||
|
Funds from operations attributable to Alexandria’s common stockholders – diluted, as adjusted: |
||||||||
|
In millions |
$ 264.4 |
$ 377.8 |
$ 856.5 |
$ 1,166.3 |
||||
|
Per share |
$ 1.54 |
$ 2.22 |
$ 5.00 |
$ 6.85 |
||||
|
(1) |
Includes $637.9 million of real estate impairment charges related to assets held for sale for 3Q26. Refer to |
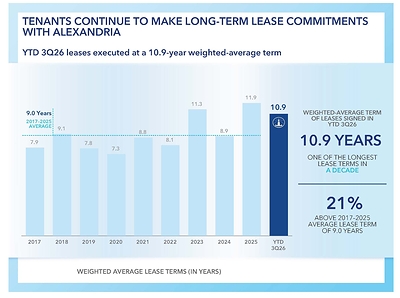
A best-in-class REIT with a high-quality and diverse tenant base, strong margins, and long lease terms
|
(As of or for the three months ended September 30, 2026, unless stated otherwise) |
|||
|
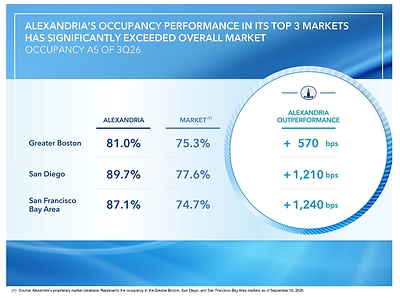
Occupancy of operating properties |
87.1 % |
||
|
Occupancy of operating properties, including executed leases with future occupancy |
90.8 % |
||
|
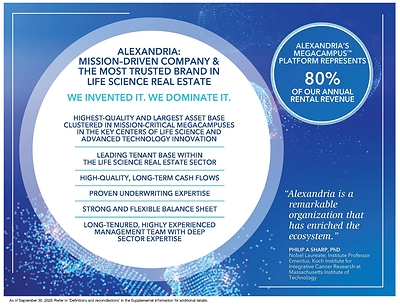
Percentage of annual rental revenue in effect from Megacampus platform |
80 % |
||
|
Percentage of annual rental revenue in effect from investment-grade or publicly |
57 % |
||
|
Operating margin |
66 % |
||
|
Adjusted EBITDA margin |
65 % |
||
|
Percentage of leases containing annual rent escalations |
97 % |
||
|
Weighted-average remaining lease term: |
|||
|
All tenants |
7.7 |
years |
|
|
Top 20 tenants |
10.0 |
years |
|
|
Strong 3Q26 tenant collections: |
|||
|
3Q26 rents and receivables collected as of October 26, 2026 |
99.9 % |
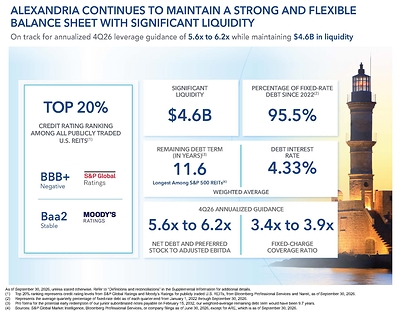
Strong and flexible balance sheet with significant liquidity; top 20% credit rating ranking among all publicly traded U.S. REITs; long-duration remaining debt term (as of 9/30/26)
- $21.01 billion in total market capitalization and $8.11 billion in total equity capitalization.
- Net debt and preferred stock to Adjusted EBITDA:
- 4Q26 annualized target: 5.6x–6.2x.
- 3Q26 annualized: 6.9x; 6.6x on a pro forma basis reflecting the October 2026 closing of the sale of our partial interest in the Campus Point by Alexandria joint venture.
- Significant liquidity of $4.56 billion and closed extension of our $5.0 billion unsecured senior line of credit to 2032.
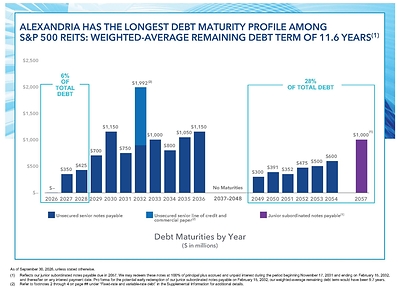
- Only 6% of our total debt matures through 2028.
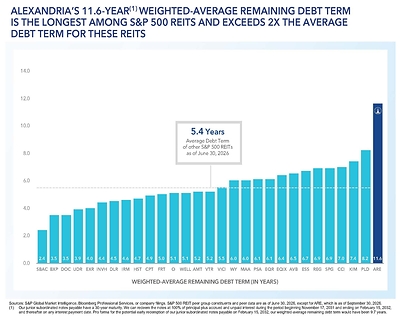
- 11.6-year weighted-average remaining debt term, the longest among S&P 500 REITs.
- Total debt and preferred stock, as adjusted, to gross assets of 30%.
- Intermediate-term goal for leverage: mid-5x range.
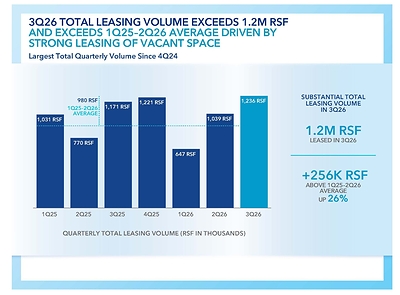
Solid 3Q26 total leasing volume exceeding 1.2 million RSF; highest total quarterly volume since 4Q24
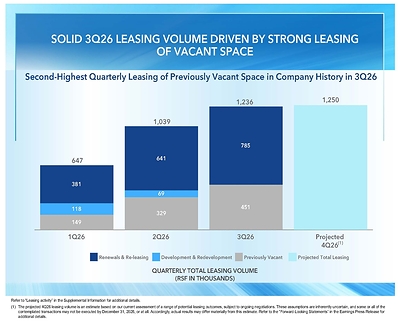
- 3Q26 total leasing volume surpassed 1.2 million RSF, exceeding the 1Q25–2Q26 quarterly average of 979,822 RSF by approximately 256,000 RSF, and representing the highest quarterly volume since 4Q24.
- Includes 450,961 RSF of leasing of previously vacant space, the second-highest quarterly amount in company history.
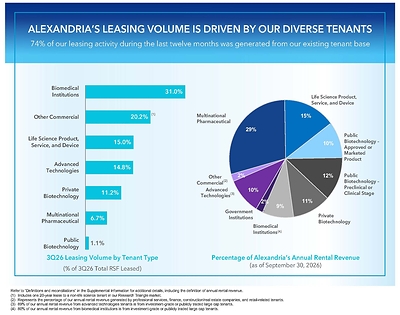
- 74% of our leasing activity during the last twelve months was generated from our existing tenant base.
|
Leasing Volume in RSF: |
3Q26 |
2Q26 |
1Q26 |
YTD 3Q26 |
|||||||
|
Leasing of previously vacant space |
450,961 |
329,148 |
148,734 |
928,843 |
|||||||
|
Leasing of development and |
— |
68,771 |
117,935 |
186,706 |
|||||||
|
450,961 |
397,919 |
266,669 |
1,115,549 |
||||||||
|
Lease renewals and re-leasing of space |
785,069 |
640,998 |
380,687 |
1,806,754 |
|||||||
|
Total leasing volume |
1,236,030 |
1,038,917 |
647,356 |
2,922,303 |
|||||||
|
Lease renewals and re-leasing of space: |
|||||||||||
|
Rental rate changes |
(2.4) % |
(0.7) % |
(15.0) % |
(5.1) % |
|||||||
|
Rental rate changes (cash basis) |
(3.3) % |
(4.3) % |
(15.8) % |
(6.9) % |
Ongoing execution of Alexandria’s capital recycling strategy
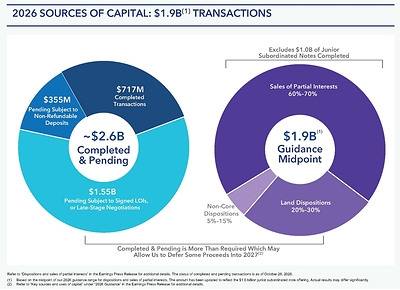
We plan to continue funding a significant portion of our capital requirements for the year ending December 31, 2026 through dispositions of land, non-core dispositions, and sales of partial interests. In October 2026, we completed the sale of an approximately 29% noncontrolling interest in Campus Point by Alexandria Megacampus for $475.0 million to a new joint venture partner.
|
Sources of capital: transactions |
Sales Price |
|
|
(dollars in millions) |
||
|
Non-core and land dispositions |
$ 242 |
|
|
Sales of partial interests |
475 |
|
|
Completed as of October 26, 2026 |
717 |
|
|
Pending transactions subject to: |
||
|
Non-refundable deposits |
355 |
|
|
Signed letters of intent and/or purchase and sale agreement late-stage negotiations |
1,548 |
|
|
2,620 |
||
|
Proceeds from dispositions and sales of partial interests in excess of 2026 guidance |
(720) |
|
|
2026 guidance midpoint for dispositions and sales of partial interests |
$ 1,900 |
Refer to “Definitions and reconciliations” in the Supplemental Information.
Occupancy of operating properties and leasing progress
|
Occupancy of operating properties as of June 30, 2026 |
86.9 % |
|
|
Key changes to occupancy of operating properties: |
||
|
Reclassification of 339,020 RSF at 311 Arsenal Street from redevelopment to |
(0.9) |
(1) |
|
Reclassification of held-for-sale properties with vacancy |
0.6 |
|
|
Net increase in occupancy primarily due to lease commencements during 3Q26 |
0.5 |
|
|
Occupancy of operating properties as of September 30, 2026 |
87.1 |
|
|
Vacant operating space with executed leases and future occupancy |
3.7 |
(2) |
|
Occupancy of operating properties as of September 30, 2026, including executed |
90.8 % |
|
(1) |
Refer to “Resolution of certain construction projects under evaluation and reduction of capital spend and funding needs” in this Earnings Press Release for additional details. |
|
(2) |
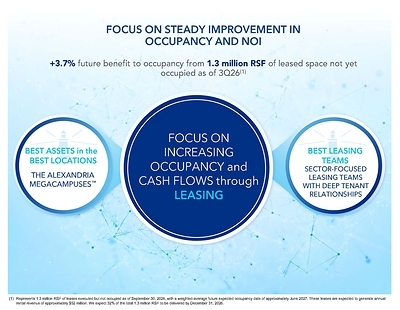
Represents executed leases aggregating 1.3 million RSF within our operating portfolio, with occupancy expected upon completion of building and/or tenant improvements. The weighted-average expected occupancy date is approximately June 2027, with expected annual rental revenue of approximately $52 million. We expect 32% of the total 1.3 million RSF to be occupied by December 31, 2026. The RSF presented excludes 686 thousand RSF of pre-leased space related to development and redevelopment projects under construction with future delivery. Refer to “New Class A/A+ development and redevelopment properties: under construction” in the Supplemental Information for additional details. |
KEY OPERATING METRICS
|
Operating metrics |
3Q26 |
YTD 3Q26 |
|||
|
Same property performance: |
|||||
|
Net operating income changes |
(6.7) % |
(1) |
(9.2) % |
(1) |
|
|
Net operating income changes (cash basis) |
(2.8) % |
(1) |
(8.4) % |
(1) |
|
|
Occupancy – current-period average |
88.1 % |
88.6 % |
|||
|
Occupancy – same-period prior-year average |
91.7 % |
92.8 % |
|||
|
Refer to “Same property comparisons” and “Net operating income” under “Definitions and reconciliations” in the Supplemental Information for additional details and their respective reconciliations from the most directly comparable financial measures presented in accordance with GAAP. |
|
|
(1) |
The decline was due to a decrease in same property occupancy, primarily driven by previously disclosed key lease expirations with expected downtime aggregating 282,878 RSF and 1.2 million RSF in 3Q26 and YTD 3Q26, respectively, with weighted-average lease expiration dates of August 2026 and April 2026, respectively. |
Resolution of certain construction projects under evaluation and reduction of capital spend and funding needs
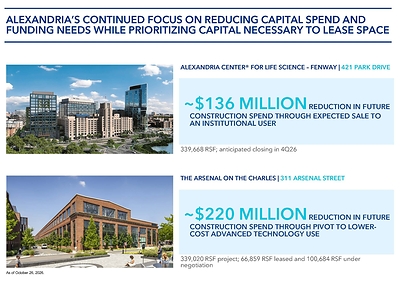
- We entered into a purchase and sale agreement with an institutional user for the sale of 421 Park Drive on the Alexandria Center® for Life Science – Fenway Megacampus, aggregating 339,668 RSF, which represents substantially all of our development project at this location. The disposition is expected to generate significant sales proceeds and to reduce future potential construction spend by approximately $136 million, with closing anticipated in 4Q26.
- We have executed leases of 66,859 RSF and have additional leases under negotiation of 100,684 RSF for advanced technology use at our project at 311 Arsenal Street on The Arsenal on the Charles Megacampus. This activity enables us to pivot the redevelopment project to a lower-cost advanced technology use, reducing future potential construction spend by approximately $220 million. As a result of this leasing progress, the entire project aggregating 339,020 RSF was reclassified from redevelopment to operating as of 3Q26.
- We continue to evaluate the business and financial strategy for three remaining projects aggregating 667,002 RSF, including options that could further reduce future construction funding requirements.
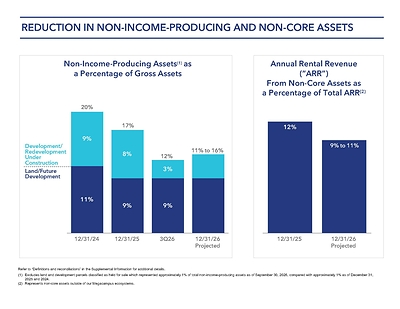
- Non-income-producing assets for 3Q26 are 12% of gross assets, a reduction of 800 bps since 4Q24.
Alexandria’s development and redevelopment pipeline delivered incremental annual net operating income of $40 million during 3Q26, with an additional $85 million expected from projects to be delivered by 4Q28
- During 3Q26, we placed into service 529,061 RSF of development and redevelopment projects across multiple submarkets. The projects were 84% occupied at delivery and generated incremental annual net operating income aggregating $40 million. 3Q26 key deliveries included:
- 198,992 RSF to Novo Nordisk for its R&D Center at 60 Sylvan Road on the Alexandria Center® for Life Science – Waltham Megacampus.
- 174,662 RSF at 99 Coolidge Avenue located on a Megacampus in Watertown.
- Annual net operating income (cash basis) from recently delivered projects is expected to increase by $67 million upon the burn-off of initial free rent, which has a weighted-average remaining period of approximately four months.
- 80% of the RSF in our total development and redevelopment pipeline is within our Megacampus ecosystems.
|
Development and Redevelopment |
Incremental Annual Net |
RSF |
Occupied/ Percentage |
||||||||
|
(dollars in millions) |
|||||||||||
|
Placed into service: |
|||||||||||
|
1H26 |
$ 58 |
532,219 |
91 % |
||||||||
|
3Q26 |
40 |
529,061 |
84 |
||||||||
|
Placed into service in YTD 3Q26 |
$ 98 |
(1) |
1,061,280 |
87 % |
|||||||
|
Expected to be placed into service:(2) |
|||||||||||
|
2027 |
$ 24 |
905,582 |
77 % |
||||||||
|
2028 |
61 |
||||||||||
|
$ 85 |
|||||||||||
|
(1) |
Excludes future incremental annual net operating income from spaces placed into service that were vacant and/or unleased at delivery. |
|
(2) |
Excludes 667,002 RSF of redevelopment projects currently under evaluation. |
Continued successful management of general and administrative expenses
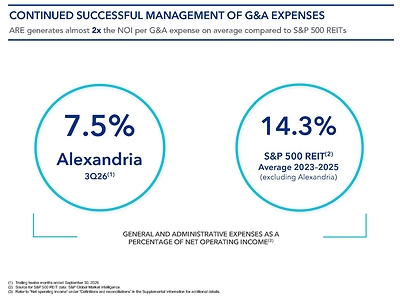
- For the trailing twelve months ended September 30, 2026, our general and administrative expenses represented 7.5% of net operating income, nearly half the average of other S&P 500 REITs for 2023–2025.
- Compared to 2024, we continue to expect approximately $76 million of cumulative general and administrative expense savings for the two-year period 2025 and 2026 (based on the midpoint of our 2026 guidance range). Some of the cost savings in 2025 were temporary, and approximately half of the cost reductions achieved in 2025 are expected to continue in 2026 (based on the midpoint of our 2026 guidance range).
Key capital events
- In August 2026, we completed a public offering of $1.00 billion aggregate principal amount of 7.250% Series A fixed-to-fixed reset rate junior subordinated notes due 2057. The notes will initially bear interest at 7.250% per year through, but excluding, February 15, 2032. Thereafter, the interest rate will reset every five years to the five-year U.S. Treasury rate plus 2.889%, subject to a minimum interest rate of 7.250%. We may elect to defer interest payments for up to five consecutive years, subject to the terms of the notes, including certain restrictions on paying dividends and repurchasing equity. We may also redeem at 100% of principal plus accrued and unpaid interest during the period beginning November 17, 2031 and ending on February 15, 2032, and thereafter on any interest payment date. This issuance supports our liquidity, capital structure, and deleveraging objectives while receiving 50% equity treatment from key rating agencies for purposes of the computations of leverage, fixed charges, and other credit metrics.
- In September 2026, we closed our amended and restated $5.0 billion unsecured senior line of credit which, among other changes, extended the maturity date from January 22, 2030 to January 22, 2032, including extension options that we control. The amendment also reduced the applicable borrowing rate to SOFR plus 0.725% from SOFR plus 0.835%. In connection with the amendment, we recognized a loss on early extinguishment of debt of approximately $3.3 million related to the partial write-off of unamortized loan fees.
- Under our common stock repurchase program authorized in December 2025, we may repurchase up to $500.0 million of our common stock through December 31, 2026. As of September 30, 2026, no shares have been repurchased under this program and $500.0 million remains available for future share repurchases.
Dividend strategy to share net cash flows from operating activities with stockholders while retaining a significant portion for reinvestment
- Common stock dividend declared of $0.72 per share for 3Q26, consistent with the preceding quarter. The declared dividend per common share reflects our commitment to maintaining the strength of our balance sheet, enhancing financial flexibility, supporting liquidity, and sharing cash flows with our stockholders.
- Significant net cash provided by operating activities, as adjusted, retained for reinvestment aggregating $2.55 billion for the years ended December 31, 2022 through 2025 and the midpoint of our 2026 guidance range.
- Dividend yield of 6.1% as of September 30, 2026 and dividend payout ratio of 47% for the three months ended September 30, 2026.
Investments
- As of September 30, 2026:
- Our non-real estate investments aggregated $1.74 billion.
- Unrealized gains presented in our consolidated balance sheet were $243.9 million, comprising gross unrealized gains and losses aggregating $322.4 million and $78.5 million, respectively.
- Investment income of $24.0 million for 3Q26, presented in our consolidated statement of operations, consisted of $16.0 million of realized gains, $21.6 million of unrealized gains, and $13.6 million of impairment charges.
2026 Guidance
September 30, 2026
(Dollars in millions, except per share amounts)
Guidance for 2026 has been updated to reflect our current view of existing market conditions and assumptions for the year ending December 31, 2026. There can be no assurance that actual results will not be materially higher or lower than these expectations. Our guidance for 2026 is subject to a number of variables and uncertainties. Refer to our discussion of “forward-looking statements” in this Earnings Press Release as well as our SEC filings, including our most recent annual report on Form 10-K and any subsequent quarterly reports on Form 10-Q.
|
Projected 2026 Funds From Operations per Share Attributable to Alexandria’s Common Stockholders – Diluted |
As of 10/26/26 |
As of 8/3/26 |
Key Changes |
|||||||
|
Funds from operations per share, as adjusted(1) |
$6.38 to $6.42 |
$6.35 to $6.45 |
No change to the midpoint, range narrowed by 6 cents |
|||||||
|
Midpoint |
$6.40 |
$6.40 |
||||||||
|
Key Credit Metrics Targets |
As of 10/26/26 |
As of 8/3/26 |
Key Changes |
|||
|
Net debt and preferred stock to Adjusted EBITDA – 4Q26 annualized |
5.6x to 6.2x |
5.6x to 6.2x |
No Change |
|||
|
Fixed-charge coverage ratio – 4Q26 annualized |
3.4x to 3.9x |
3.6x to 4.1x |
0.2x reduction(2) |
|||
|
As of 10/26/26 |
As of 8/3/26 |
|||||||||||
|
Key Sources and Uses of Capital |
Range |
Midpoint |
Certain |
|||||||||
|
Sources of capital: |
||||||||||||
|
Net cash provided by operating activities, as adjusted |
$ 475 |
$ 575 |
$ 525 |
$ 525 |
||||||||
|
Dispositions and sales of partial interests |
1,100 |
2,700 |
1,900 |
(3) |
2,900 |
|||||||
|
Total sources of capital |
$ 1,575 |
$ 3,275 |
$ 2,425 |
$ 3,425 |
||||||||
|
Uses of capital: |
||||||||||||
|
Construction(4) |
$ 1,500 |
$ 2,000 |
$ 1,750 |
$ 1,750 |
||||||||
|
Reduction in unsecured debt |
75 |
1,275 |
675 |
See below |
1,675 |
|||||||
|
Total uses of capital |
$ 1,575 |
$ 3,275 |
$ 2,425 |
$ 3,425 |
||||||||
|
Reduction in unsecured debt (included above): |
||||||||||||
|
Repayment of unsecured senior notes payable with 2026 maturities |
$ 650 |
$ 650 |
$ 650 |
$ |
650 |
$ 650 |
||||||
|
Tender offers for partial principal repayments of unsecured senior notes payable |
952 |
952 |
952 |
$ |
952 |
952 |
||||||
|
Issuance of unsecured senior notes payable |
(750) |
(750) |
(750) |
$ |
(750) |
(750) |
||||||
|
Issuance of junior subordinated notes payable(3) |
(1,000) |
(1,000) |
(1,000) |
$ |
(1,000) |
— |
||||||
|
Unsecured senior line of credit, commercial paper, and other |
223 |
1,423 |
823 |
823 |
||||||||
|
Reduction in unsecured debt |
$ 75 |
$ 1,275 |
$ 675 |
$ 1,675 |
||||||||
Refer to “Definitions and reconciliations” in the Supplemental Information for additional details on key credit metrics.
|
(1) |
Refer to “Funds from operations and funds from operations, as adjusted, attributable to Alexandria Real Estate Equities, Inc.’s common stockholders” under “Definitions and reconciliations” in the Supplemental Information for additional details. |
|
(2) |
Reduction primarily reflects the $1.00 billion issuance of 7.250% Series A fixed-to-fixed reset rate junior subordinated notes due 2057, as further discussed in footnote 3 below. |
|
(3) |
In August 2026, we issued $1.00 billion of 7.250% Series A fixed-to-fixed reset rate junior subordinated notes due 2057, allowing us to reduce the midpoint of our 2026 dispositions and sales of partial interests guidance by $1.0 billion. The proceeds from this issuance support our capital structure and deleveraging objectives, and the notes receive 50% equity treatment from key rating agencies for the computation of key credit metrics. Refer to the Earnings Press Release in the Supplemental Information for additional details. We do not anticipate the issuance of any common equity during 2026. As of October 26, 2026, completed dispositions and sales of partial interests aggregated $716.8 million, our share of pending dispositions and sales of partial interests subject to non-refundable deposits aggregated $355.4 million and signed letters of intent and/or purchase and sale agreement late-stage negotiations aggregated $1.55 billion. These transactions aggregate approximately $2.62 billion, exceeding the $1.90 billion midpoint of our 2026 guidance and potentially providing advanced funding of our 2027 capital needs, whereby certain dispositions and sales of partial interests may be completed in 2026 with proceeds deferred or available to be drawn in 2027, subject to timing and market conditions. |
|
(4) |
We continue to apply a disciplined approach to reduce construction spending for 2027 and seek to prioritize leased projects with high incremental returns. We expect 2027 construction spending to primarily focus on: (i) revenue- and non-revenue-enhancing capital expenditures, which are expected to represent the majority of spend, approximately half of which is associated with space that is already leased or under lease negotiations, in order to support the leasing of vacant space and renewals and re-leasing of space at our operating properties and (ii) construction spending required to complete our development and redevelopment projects that are expected to stabilize through 2028 and are 77% leased/negotiating. |
|
As of 10/26/26 |
As of 8/3/26 |
Key Changes to Midpoint |
|||||||||
|
Key Assumptions |
Low |
High |
Low |
High |
|||||||
|
Occupancy of operating properties as of December 31, 2026 |
86.2 % |
87.8 % |
86.2 % |
87.8 % |
No Change |
||||||
|
Same property performance: |
|||||||||||
|
Net operating income changes |
(10.5) % |
(8.5) % |
(10.5) % |
(8.5) % |
|||||||
|
Net operating income changes (cash basis) |
(10.5) % |
(8.5) % |
(10.5) % |
(8.5) % |
|||||||
|
Lease renewals and re-leasing of space: |
|||||||||||
|
Rental rate changes |
(9.0) % |
(1.0) % |
(9.0) % |
(1.0) % |
|||||||
|
Rental rate changes (cash basis) |
(15.0) % |
(7.0) % |
(15.0) % |
(7.0) % |
|||||||
|
Straight-line rent revenue |
$ 40 |
$ 70 |
$ 45 |
$ 75 |
$5 million reduction(1) |
||||||
|
General and administrative expenses |
$ 134 |
$ 154 |
$ 134 |
$ 154 |
No Change |
||||||
|
Capitalization of interest |
$ 220 |
$ 260 |
$ 220 |
$ 260 |
|||||||
|
Interest expense |
$ 260 |
$ 300 |
$ 260 |
$ 300 |
No Change(2) |
||||||
|
Realized gains on non-real estate investments(3) |
$ 50 |
$ 80 |
$ 60 |
$ 90 |
$10 million reduction(3) |
||||||
|
(1) |
Reduction driven primarily by write-offs and reserves of deferred rent related to tenant wind-downs. Our 2026 guidance assumes a $30 million to $35 million reduction in funds from operations related to potential tenant wind-downs, of which approximately $30 million was recognized YTD through 3Q26, including approximately $16 million recognized in 3Q26. |
|
(2) |
We expect 2026 interest expense to be near the high-end of the range, reflecting, in part, interest expense associated with the $1.0 billion issuance of junior subordinated notes in August 2026. |
|
(3) |
Represents realized gains and losses included in funds from operations per share – diluted, as adjusted. Excludes unrealized gains and losses and significant gains and impairments realized on non-real estate investments, if any. The midpoint of our revised guidance range for 2026 realized gains on non-real estate investments was reduced by $10 million, primarily due to certain transactions previously expected to close in 2026 that are now expected to close in 2027. Refer to “Investments” in the Supplemental Information for additional details. |
Summary of key items that may impact 2026 and 2027 results
1) Potential tenant wind-downs
- Our 2026 guidance includes a $30 million to $35 million reduction in funds from operations for potential tenant wind-downs, of which approximately $30 million was recognized during the nine months ended September 30, 2026, including approximately $16 million recognized in 3Q26.
- Based upon current market conditions, we preliminarily estimate at least a similar level of reduction in funds from operations may be necessary in 2027.
- Depending on the timing and magnitude of the specific tenant wind-downs, we anticipate that 2027 occupancy may also be negatively impacted.
2) Development-related other income
- During the nine months ended September 30, 2026, we recognized development fees and other related revenues of approximately $8.0 million, or $11 million annualized, most of which are expected to cease by the end of 2026 as we complete the respective projects.
3) Development and redevelopment projects under business and financial strategy evaluation
- We have three redevelopment projects for which the business and financial strategies continue to be evaluated, including whether to continue construction of laboratory improvements, pause construction, pursue lower-investment construction alternatives (including a pivot to advanced technology use), or pursue a disposition. Refer to “New Class A/A+ development and redevelopment properties: under construction” in the Supplemental Information for additional details.
- If we elect to continue to pursue construction of laboratory improvements for these projects, the earliest deliveries of these projects are in 2028.
- If we elect to pursue lower-investment construction alternatives (including a pivot to advanced technology use), we expect these projects would have lower rental rates and stabilized yields compared to our initial underwriting. The incremental capital required for alternative-use construction and corresponding rental rates earned are generally lower than those associated with laboratory improvements.
- As of 3Q26, we have executed leases for 66,859 RSF and have additional leases under negotiation for 100,684 RSF for advanced technology use at our project at 311 Arsenal Street in The Arsenal on the Charles Megacampus. This activity enables us to pivot the redevelopment project to a lower-cost alternative use at lower rental rates and stabilized yields than our initial underwriting. Therefore, we placed this project, aggregating 339,020 RSF, into operation during 3Q26 and included it in our operating occupancy as of September 30, 2026. Refer to the Earnings Press Release and “Leasing Activity” in the Supplemental Information for additional details.
- In addition, we entered into a purchase and sale agreement with an institutional user for the sale of our development project at 421 Park Drive on the Alexandria Center® for Life Science – Fenway Megacampus aggregating 339,668 RSF. The disposition is expected to close in 4Q26, resulting in significant sales proceeds and reducing future construction spending by approximately $136 million.
4) Capitalization of interest
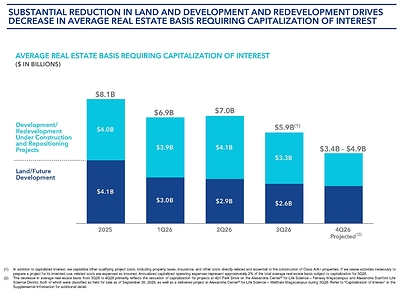
- Our average real estate basis capitalized during 3Q26 was $5.87 billion. As of September 30, 2026, our real estate basis that continued to qualify for capitalization declined to $4.46 billion, primarily driven by the cessation of capitalization on our projects at 421 Park Drive on the Alexandria Center® for Life Science – Fenway Megacampus and Alexandria Stanford Life Science District, both of which were classified as held for sale as of September 30, 2026, as well as a delivered project at Alexandria Center® for Life Science – Waltham Megacampus in September 2026. During 4Q26, we expect the average real estate basis capitalized to range from $3.4 billion to $4.9 billion. Refer to “Capitalization of interest” in the Supplemental Information for additional detail.
- At each milestone date, we evaluate, on an asset-by-asset basis, whether to (i) proceed with additional pre-construction and/or construction activities based on leasing demand and/or market conditions, (ii) pause future investments, or (iii) consider potential dispositions or sales of partial interests of these real estate assets. If we cease the activities necessary to prepare a project for its intended use, costs related to such project, including interest, payroll, property taxes, insurance, and other costs directly related and essential to the construction of Class A/A+ properties, are expensed as incurred. During 3Q26, annualized capitalized operating expenses represented approximately 2% of the total average real estate basis subject to capitalization.
5) 2027 Key lease expirations
- We estimate that 1.4 million RSF of leases expiring in 2027, with approximately $100.5 million of annual rental revenue, will have downtime after lease expiration. These 2027 expirations have a weighted-average contractual lease expiration date in March 2027 and an expected weighted-average downtime ranging from 9 to 24 months. Refer to “Contractual lease expirations” in the Supplemental Information for additional details.
|
2027 Key Lease Expirations |
||||||
|
RSF |
Annual Rental |
Weighted-Average |
Weighted-Average |
|||
|
1,377,960 |
$100.5 million |
March 2027 |
9 to 24 months |
|||
We expect to introduce 2027 guidance and related key assumptions, and 2027 key sources and uses of capital at our Investor Day on December 2, 2026, consistent with our historical practice.
Summary of key items that may impact 2027 and 2028 results
The following key considerations for 2027 and 2028 reflect our preliminary expectations based on current market conditions. These expectations could change materially and are subject to a variety of factors, including industry, governmental, geopolitical, and macroeconomic conditions, including changes in interest rates, as well as other factors described in our SEC filings, including our most recent annual report on Form 10-K and any subsequent quarterly reports on Form 10-Q.
1) Operating occupancy
- For the year ending December 31, 2027, we expect average operating occupancy to temporarily decline relative to our projected operating occupancy as of December 31, 2026, primarily due to expected downtime associated with the 1.4 million RSF of 2027 key lease expirations disclosed in “Contractual lease expirations” in the Supplemental Information, as well as the potential for tenant wind-downs.
- For the year ending December 31, 2028, we expect average operating occupancy to improve relative to our projected average operating occupancy for the year ending December 31, 2027, driven by the lease-up of temporary vacancy partially offset by approximately 718 thousand RSF of 2028 key lease expirations with expected downtime as disclosed in “Contractual lease expirations” in the Supplemental Information.
2) Same property performance
- For the year ending December 31, 2027, we expect same property net operating income performance to improve compared with the midpoint of our guidance range for 2026 but remain negative, primarily due to the expected temporary year-over-year decline in average operating occupancy, including the impact of expected downtime associated with 1.4 million RSF of 2027 key lease expirations.
- For the year ending December 31, 2028, we expect same property net operating income performance to improve compared with 2027, primarily driven by operating occupancy growth and the lease-up of vacant space, subject to leasing and market conditions.
3) Construction spending
- For 2027, we continue to apply a disciplined approach to reduce construction spending and we seek to prioritize leased projects with high incremental returns. We expect 2027 construction spending to primarily focus on (i) revenue- and non-revenue-enhancing capital expenditures, which are expected to represent the majority of spend, approximately half of which is associated with space that is leased or under lease negotiations, in order to support the leasing of vacant space and renewals and re-leasing of space at our operating properties and (ii) construction spending required to complete our development and redevelopment projects that are expected to stabilize through 2028 and are 77% leased/negotiating as of October 26, 2026.
- For 2028, we expect a further decline in construction spending relative to 2027, primarily driven by lower development and redevelopment spending. Construction spending on revenue- and non-revenue-enhancing capital expenditures related to our operating portfolio is expected to continue to support the lease-up of temporary vacancy, subject to leasing and market conditions.
4) Transactional and other capital sources
- For 2027, capital will be required to fund construction spending as we continue to prudently manage our key credit metrics, including net debt and preferred stock to Adjusted EBITDA ratio. In general, we expect to rely on asset recycling transactions, and other sources of cost-effective capital to support the achievement of our 2027 key credit metric ratio targets, including net debt and preferred stock to Adjusted EBITDA.
- For 2028, if we have growth in Adjusted EBITDA, we may use incremental long-term debt to fund a portion of our capital needs on a leverage neutral basis. In addition, we may use asset recycling and other sources of cost-effective capital to support the achievement of our 2028 key credit metric ratio targets, including net debt and preferred stock to Adjusted EBITDA.
Dispositions and Sales of Partial Interests
September 30, 2026
(Dollars in thousands)
|
Date of |
Interest |
Square Footage |
Price (Our Share) |
||||||||||
|
Property |
Submarket/Market |
Operating |
Future |
||||||||||
|
Completed in 1H26 |
$ 7,350 |
||||||||||||
|
Non-core and land dispositions completed in 3Q26: |
|||||||||||||
|
3825 and 3875 Fabian Way(1) |
Palo Alto/San Francisco Bay Area |
7/14/26 |
100 % |
228,000 |
250,000 |
163,000 |
|||||||
|
One Hampshire Street(2) |
Cambridge/Greater Boston |
8/21/26 |
100 % |
104,956 |
— |
44,900 |
|||||||
|
3911, 3931, 4025, 4031, 4045, and 4075 Sorrento Valley Boulevard(3) |
Sorrento Valley/San Diego |
9/23/26 |
100 % |
95,814 |
144,000 |
26,500 |
|||||||
|
Dispositions completed in 3Q26 |
234,400 |
(4) |
|||||||||||
|
Total dispositions completed in YTD 3Q26 |
241,750 |
||||||||||||
|
Completed in October 2026: |
|||||||||||||
|
Sales of partial interests: |
|||||||||||||
|
Campus Point by Alexandria(5) |
University Town Center/San Diego |
10/23/26 |
(5) |
1,586,697 |
366,816 |
475,000 |
|||||||
|
Total completed 2026 dispositions and sales of partial interests as of October 26, 2026 |
716,750 |
||||||||||||
|
Our share of pending dispositions and sales of partial interests subject to: |
|||||||||||||
|
Non-refundable deposits |
355,400 |
||||||||||||
|
Signed letters of intent and/or purchase and sale agreement late-stage negotiations |
1,547,850 |
||||||||||||
|
2,620,000 |
|||||||||||||
|
Proceeds from dispositions and sales of partial interests in excess of 2026 guidance |
(720,000) |
||||||||||||
|
2026 guidance midpoint for dispositions and sales of partial interests |
$ 1,900,000 |
||||||||||||
|
2026 guidance range for dispositions and sales of partial interests |
$1,100,000 – $2,700,000 |
||||||||||||
|
Weighted-average projected completion date of 2026 dispositions and sales of partial interests |
November 2026 |
(7) |
|||||||||||
|
(1) |
Represents one future development project aggregating 250,000 SF at 3825 Fabian Way and one fully leased operating building aggregating 228,000 RSF at 3875 Fabian Way in our Palo Alto submarket. These assets were acquired in 2019 with the intent to develop them for life science use. However, due to the project’s macroeconomic outlook, the assets no longer aligned with our strategy and were sold to a residential developer. |
|
(2) |
Represents one vacant office property that was originally acquired with the intent to redevelop for life science use and expand our Megacampus ecosystem. The asset was sold due to the macroeconomic outlook for the project and the significant capital required to redevelop and lease the property. |
|
(3) |
Represents five operating properties, primarily comprising non-laboratory space, and one land parcel. As of 2Q26, these operating properties were 30% occupied with a weighted-average lease term of 2.4 years, and were sold due to the significant capital that would have been required to convert these properties through redevelopment for laboratory use and their misalignment with our Megacampus strategy. |
|
(4) |
Our share of dispositions completed during the three months ended September 30, 2026 had annual net operating income of $4.4 million (based on 2Q26 annualized results) with a weighted-average disposition date of July 29, 2026. |
|
(5) |
In October 2026, we completed the sale of an approximately 29% noncontrolling interest in the Campus Point by Alexandria Megacampus for $475.0 million. We expect our new partner’s initial share of the annual distributions to approximate 5.5% of its $475.0 million capital contribution. Upon completion of the sale, our ownership interest decreased from 59% as of September 30, 2026 to approximately 30%. We expect to fund the majority of future construction costs at the Megacampus, which is expected to reduce the ownership interests of our new joint venture partner and existing joint venture partner over time to below 20% and 30%, respectively, and increase our ownership interest to over 50%. We retained control and therefore continue to consolidate the properties held by the real estate joint venture. Accordingly, we accounted for the $44.2 million difference between the consideration received and the book value of our interest sold as an increase to additional paid-in capital, with no gain recognized in earnings. |
|
(6) |
Refer to “Key Sources and Uses of Capital” under “2026 Guidance” in the Earnings Press Release for additional details. |
|
(7) |
Including the impact of the $1.0 billion junior subordinated notes issued during 3Q26, the weighted-average projected completion date of these sources of capital is expected to be October 2026. |
Earnings Call Information and About the Company
September 30, 2026
We will host a conference call on Tuesday, October 27, 2026, at 2:00 p.m. Eastern Time (“ET”)/11:00 a.m. Pacific Time (“PT”), which is open to the general public, to discuss our financial and operating results for the third quarter ended September 30, 2026. To participate in this conference call, dial (833) 366-1125 or (412) 902-6738 shortly before 2:00 p.m. ET/11:00 a.m. PT and ask the operator to join the call for Alexandria Real Estate Equities, Inc. The audio webcast can be accessed at www.are.com in the “For Investors” section. A replay of the call will be available for a limited time from 4:00 p.m. ET/1:00 p.m. PT on Tuesday, October 27, 2026, through 4:00 p.m. ET on Tuesday, November 3, 2026. The replay number is (855) 669-9658 or (412) 317-0088, and the access code is 6457127.
Additionally, a copy of this Earnings Press Release and Supplemental Information for the third quarter ended September 30, 2026 is available in the “For Investors” section of our website at www.are.com or by following this link: https://www.are.com/fs/2026q3.pdf.
For any questions, please contact corporateinformation@are.com; Joel S. Marcus, executive chairman and founder; Peter M. Moglia, chief executive officer and chief investment officer; Marc E. Binda, chief financial officer and treasurer; or Paula Schwartz, managing director of Rx Communications Group, at (917) 633-7790.
About the Company
Alexandria Real Estate Equities, Inc. (NYSE: ARE), an S&P 500® company, is a best-in-class, mission-driven life science REIT making a positive and lasting impact on the world. With our founding in 1994, Alexandria pioneered the life science real estate niche. Alexandria is the preeminent and longest-tenured owner, operator, and developer of collaborative Megacampus ecosystems in AAA life science and advanced technology innovation cluster locations, including Greater Boston, San Diego, the San Francisco Bay Area, Seattle, Maryland, Research Triangle, and New York City. As of September 30, 2026, Alexandria has a total market capitalization of $21.01 billion and an asset base that includes 36.5 million RSF of operating properties and 1.9 million RSF of Class A/A+ properties undergoing construction. Alexandria has a long-standing and proven track record of developing Class A/A+ properties clustered in highly dynamic and collaborative Megacampus environments that enhance our tenants’ ability to successfully recruit and retain world-class talent and inspire productivity, efficiency, creativity, and success. Alexandria also provides strategic capital to transformative life science companies through our venture capital platform. We believe our unique business model and diligent underwriting ensure a high-quality and diverse tenant base that results in higher occupancy levels, longer lease terms, higher rental income, higher returns, and greater long-term asset value. For more information on Alexandria, please visit www.are.com.
Forward-Looking Statements
This document includes “forward-looking statements” within the meaning of Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended. Such forward-looking statements include, without limitation, statements regarding our projected 2026 funds from operations per share, projected 2026 funds from operations per share, as adjusted, projected net operating income, and our projected sources and uses of capital. You can identify the forward-looking statements by their use of forward-looking words, such as “forecast,” “guidance,” “goals,” “projects,” “estimates,” “anticipates,” “believes,” “expects,” “intends,” “may,” “plans,” “seeks,” “should,” “targets,” or “will,” or the negative of those words or similar words. These forward-looking statements are based on our current expectations, beliefs, projections, future plans and strategies, anticipated events or trends, and similar expressions concerning matters that are not historical facts, as well as a number of assumptions concerning future events. There can be no assurance that actual results will not be materially higher or lower than these expectations. These statements are subject to risks, uncertainties, assumptions, and other important factors that could cause actual results to differ materially from the results discussed in the forward-looking statements. Factors that might cause such a difference include, without limitation, our failure to obtain capital (debt, construction financing, and/or equity) or refinance debt maturities, lower than expected yields, increased interest rates and operating costs, adverse economic or real estate developments in our markets, our failure to successfully place into service and lease any properties undergoing development or redevelopment and our existing space held for future development or redevelopment (including new properties acquired for that purpose), our failure to successfully operate or lease acquired properties, decreased rental rates, increased vacancy rates or failure to renew or replace expiring leases, defaults on or non-renewal of leases by tenants, our failure to complete planned dispositions and sales of partial interests on anticipated terms or timing, adverse general and local economic conditions, an unfavorable capital market environment, decreased leasing activity or lease renewals, failure to obtain LEED and other healthy building certifications and efficiencies, and other risks and uncertainties detailed in our filings with the Securities and Exchange Commission (“SEC”). Accordingly, you are cautioned not to place undue reliance on such forward-looking statements. All forward-looking statements are made as of the date of this Earnings Press Release and Supplemental Information, and unless otherwise stated, we assume no obligation to update this information and expressly disclaim any obligation to update or revise any forward-looking statements, whether as a result of new information, future events, or otherwise. For more discussion relating to risks and uncertainties that could cause actual results to differ materially from those anticipated in our forward-looking statements, and risks to our business in general, please refer to our SEC filings, including our most recent annual report on Form 10-K and any subsequent quarterly reports on Form 10-Q.
This document is not an offer to sell or a solicitation to buy securities of Alexandria Real Estate Equities, Inc. Any offers to sell or solicitations to buy our securities shall be made only by means of a prospectus approved for that purpose. Unless otherwise indicated, the “Company,” “Alexandria,” “ARE,” “we,” “us,” and “our” refer to Alexandria Real Estate Equities, Inc. and our consolidated subsidiaries. Alexandria®, Lighthouse Design® logo, Building the Future of Life-Changing Innovation®, That’s What’s in Our DNA®, Megacampus™, At the Vanguard and Heart of the Life Science Ecosystem™, Alexandria Center®, Alexandria Technology Square®, Alexandria Technology Center®, and Alexandria Innovation Center® are copyrights and trademarks of Alexandria Real Estate Equities, Inc. All other company names, trademarks, and logos referenced herein are the property of their respective owners.
|
Consolidated Statements of Operations |
||||||||||||||
|
Three Months Ended |
Nine Months Ended |
|||||||||||||
|
9/30/26 |
6/30/26 |
3/31/26 |
12/31/25 |
9/30/25 |
9/30/26 |
9/30/25 |
||||||||
|
Revenues: |
||||||||||||||
|
Income from rentals |
$ 653,618 |
$ 643,210 |
$ 653,013 |
$ 728,872 |
$ 735,849 |
$ 1,949,841 |
$ 2,216,303 |
|||||||
|
Other income |
17,564 |
19,574 |
18,009 |
25,542 |
16,095 |
55,147 |
55,839 |
|||||||
|
Total revenues |
671,182 |
662,784 |
671,022 |
754,414 |
751,944 |
2,004,988 |
2,272,142 |
|||||||
|
Expenses: |
||||||||||||||
|
Rental operations |
227,931 |
207,336 |
224,142 |
232,543 |
239,234 |
659,409 |
690,062 |
|||||||
|
General and administrative |
40,915 |
36,861 |
34,685 |
28,020 |
29,224 |
112,461 |
89,027 |
|||||||
|
Interest |
79,687 |
64,342 |
64,584 |
65,674 |
54,852 |
208,613 |
161,024 |
|||||||
|
Depreciation and amortization |
304,419 |
304,384 |
305,441 |
322,063 |
340,230 |
914,244 |
1,028,415 |
|||||||
|
Impairment of real estate |
637,904 |
(1) |
222,470 |
5,499 |
1,717,188 |
323,870 |
865,873 |
485,630 |
||||||
|
Total expenses |
1,290,856 |
835,393 |
634,351 |
2,365,488 |
987,410 |
2,760,600 |
2,454,158 |
|||||||
|
Equity in earnings (losses) of unconsolidated real estate joint ventures |
75 |
413 |
(147) |
(304) |
201 |
341 |
(9,327) |
|||||||
|
Investment income (losses) |
23,990 |
133,227 |
(4,582) |
(3,890) |
28,161 |
152,635 |
(52,453) |
|||||||
|
(Loss) gain on early extinguishment of debt |
(3,323) |
— |
366,435 |
— |
(107) |
363,112 |
(107) |
|||||||
|
Gain on sales of real estate |
— |
— |
— |
619,914 |
9,366 |
— |
22,531 |
|||||||
|
Net (loss) income |
(598,932) |
(38,969) |
398,377 |
(995,354) |
(197,845) |
(239,524) |
(221,372) |
|||||||
|
Net income attributable to noncontrolling interests |
(38,754) |
(33,814) |
(36,724) |
(85,521) |
(34,909) |
(109,292) |
(127,323) |
|||||||
|
Net (loss) income attributable to Alexandria Real Estate Equities, Inc.’s |
(637,686) |
(72,783) |
361,653 |
(1,080,875) |
(232,754) |
(348,816) |
(348,695) |
|||||||
|
Net income attributable to unvested restricted stock awards |
(766) |
(908) |
(2,779) |
(965) |
(2,183) |
(2,603) |
(7,452) |
|||||||
|
Net (loss) income attributable to Alexandria Real Estate Equities, Inc.’s |
$ (638,452) |
$ (73,691) |
$ 358,874 |
$ (1,081,840) |
$ (234,937) |
$ (351,419) |
$ (356,147) |
|||||||
|
Net (loss) income per share attributable to Alexandria Real Estate Equities, |
||||||||||||||
|
Basic |
$ (3.74) |
$ (0.43) |
$ 2.10 |
$ (6.35) |
$ (1.38) |
$ (2.06) |
$ (2.09) |
|||||||
|
Diluted |
$ (3.74) |
$ (0.43) |
$ 2.10 |
$ (6.35) |
$ (1.38) |
$ (2.06) |
$ (2.09) |
|||||||
|
Weighted-average shares of common stock outstanding: |
||||||||||||||
|
Basic |
170,751 |
170,718 |
170,598 |
170,394 |
170,181 |
170,689 |
170,278 |
|||||||
|
Diluted |
170,751 |
170,718 |
170,867 |
170,394 |
170,181 |
170,689 |
170,278 |
|||||||
|
Dividends declared per share of common stock |
$ 0.72 |
$ 0.72 |
$ 0.72 |
$ 0.72 |
$ 1.32 |
$ 2.16 |
$ 3.96 |
|||||||
|
(1) Refer to “Funds from operations and funds from operations per share” in the Earnings Press Release for additional details regarding impairment of real estate. |
|
Consolidated Balance Sheets |
||||||||||
|
9/30/26 |
6/30/26 |
3/31/26 |
12/31/25 |
9/30/25 |
||||||
|
Assets |
||||||||||
|
Investments in real estate |
$ 28,426,999 |
$ 29,125,895 |
$ 28,830,116 |
$ 28,689,996 |
$ 31,743,917 |
|||||
|
Investments in unconsolidated real estate joint ventures |
28,580 |
28,910 |
30,520 |
30,677 |
39,601 |
|||||
|
Cash and cash equivalents |
508,855 |
470,449 |
418,720 |
549,062 |
579,474 |
|||||
|
Restricted cash |
4,908 |
4,690 |
4,665 |
4,693 |
4,705 |
|||||
|
Tenant receivables |
6,168 |
7,661 |
7,362 |
6,672 |
6,409 |
|||||
|
Deferred rent |
1,210,911 |
1,209,722 |
1,200,047 |
1,179,403 |
1,257,378 |
|||||
|
Deferred leasing costs |
452,164 |
453,761 |
456,405 |
458,311 |
505,241 |
|||||
|
Investments |
1,735,673 |
1,685,695 |
1,536,419 |
1,501,249 |
1,537,638 |
|||||
|
Other assets |
1,677,464 |
1,645,443 |
1,683,143 |
1,661,772 |
1,700,785 |
|||||
|
Total assets |
$ 34,051,722 |
$ 34,632,226 |
$ 34,167,397 |
$ 34,081,835 |
$ 37,375,148 |
|||||
|
Liabilities, Noncontrolling Interests, and Equity |
||||||||||
|
Unsecured senior notes payable |
$ 10,820,687 |
$ 10,818,366 |
$ 11,166,009 |
$ 12,047,394 |
$ 12,044,999 |
|||||
|
Junior subordinated notes payable |
985,143 |
— |
— |
— |
— |
|||||
|
Unsecured senior line of credit and commercial paper |
1,091,166 |
1,994,508 |
1,353,986 |
353,161 |
1,548,542 |
|||||
|
Accounts payable, accrued expenses, and other liabilities |
2,604,418 |
2,513,526 |
2,154,782 |
2,397,073 |
2,432,726 |
|||||
|
Dividends payable |
131,999 |
130,468 |
128,880 |
127,771 |
230,603 |
|||||
|
Total liabilities |
15,633,413 |
15,456,868 |
14,803,657 |
14,925,399 |
16,256,870 |
|||||
|
Commitments and contingencies |
||||||||||
|
Redeemable noncontrolling interests |
9,119 |
9,119 |
9,234 |
58,788 |
58,662 |
|||||
|
Alexandria Real Estate Equities, Inc.’s stockholders’ equity: |
||||||||||
|
Common stock |
1,708 |
1,707 |
1,707 |
1,705 |
1,703 |
|||||
|
Additional paid-in capital |
14,839,182 |
15,585,296 |
15,763,321 |
15,497,760 |
16,669,802 |
|||||
|
Accumulated other comprehensive loss |
(33,691) |
(33,027) |
(30,936) |
(29,395) |
(32,203) |
|||||
|
Alexandria Real Estate Equities, Inc.’s stockholders’ equity |
14,807,199 |
15,553,976 |
15,734,092 |
15,470,070 |
16,639,302 |
|||||
|
Noncontrolling interests |
3,601,991 |
3,612,263 |
3,620,414 |
3,627,578 |
4,420,314 |
|||||
|
Total equity |
18,409,190 |
19,166,239 |
19,354,506 |
19,097,648 |
21,059,616 |
|||||
|
Total liabilities, noncontrolling interests, and equity |
$ 34,051,722 |
$ 34,632,226 |
$ 34,167,397 |
$ 34,081,835 |
$ 37,375,148 |
|||||
|
Funds From Operations and Funds From Operations per Share |
|
The following table presents a reconciliation of net income (loss) attributable to Alexandria’s common stockholders, the most directly comparable financial measure presented in accordance with U.S. |
|
Three Months Ended |
Nine Months Ended |
|||||||||||||
|
9/30/26 |
6/30/26 |
3/31/26 |
12/31/25 |
9/30/25 |
9/30/26 |
9/30/25 |
||||||||
|
Net (loss) income attributable to Alexandria’s common stockholders – basic and diluted |
$ (638,452) |
$ (73,691) |
$ 358,874 |
$(1,081,840) |
$ (234,937) |
$ (351,419) |
$ (356,147) |
|||||||
|
Depreciation and amortization of real estate assets |
302,240 |
302,238 |
303,296 |
319,865 |
338,182 |
907,774 |
1,021,292 |
|||||||
|
Noncontrolling share of depreciation and amortization from consolidated real estate JVs |
(32,458) |
(31,518) |
(29,473) |
(39,942) |
(45,327) |
(93,449) |
(114,785) |
|||||||
|
Our share of depreciation and amortization from unconsolidated real estate JVs |
858 |
805 |
914 |
855 |
852 |
2,577 |
2,848 |
|||||||
|
Gain on sales of real estate |
— |
— |
— |
(307,132) |
(9,824) |
— |
(22,989) |
|||||||
|
Impairment of real estate – rental properties and land |
637,904 |
(1) |
222,470 |
5,499 |
1,439,303 |
323,870 |
865,873 |
454,960 |
||||||
|
Allocation to unvested restricted stock awards |
(1,042) |
(2,201) |
(2,181) |
(1,903) |
(1,648) |
(7,141) |
(3,590) |
|||||||
|
Funds from operations attributable to Alexandria’s common stockholders – diluted(2) |
269,050 |
418,103 |
636,929 |
329,206 |
371,168 |
1,324,215 |
981,589 |
|||||||
|
Unrealized (gains) losses on non-real estate investments |
(21,563) |
(131,933) |
10,332 |
(98,548) |
(18,515) |
(143,164) |
71,568 |
|||||||
|
Significant realized losses on non-real estate investments |
— |
— |
— |
103,329 |
— |
— |
— |
|||||||
|
Impairment of non-real estate investments |
13,580 |
(3) |
8,998 |
12,448 |
20,181 |
25,139 |
35,026 |
75,535 |
||||||
|
Impairment of real estate |
— |
— |
— |
12,619 |
— |
— |
39,343 |
|||||||
|
Loss (gain) on early extinguishment of debt |
3,323 |
— |
(366,435) |
— |
107 |
(363,112) |
107 |
|||||||
|
Acceleration of stock compensation expense due to executive officer resignation |
— |
— |
— |
2,455 |
— |
— |
— |
|||||||
|
(Decrease) increase in provision for expected credit losses on financial instruments |
— |
— |
— |
(341) |
— |
— |
285 |
|||||||
|
Allocation to unvested restricted stock awards |
33 |
909 |
2,674 |
(363) |
(74) |
3,496 |
(2,156) |
|||||||
|
Funds from operations attributable to Alexandria’s common stockholders – diluted, as |
$ 264,423 |
$ 296,077 |
$ 295,948 |
$ 368,538 |
$ 377,825 |
$ 856,461 |
$ 1,166,271 |
|||||||
Refer to “Definitions and reconciliations” in the Supplemental Information for additional details.
|
(1) |
Primarily reflects impairment charges to reduce the carrying amounts of real estate assets classified as held for sale as of 3Q26 to their respective estimated fair values less costs to sell, including (i) $343.3 million related to a development project in our Fenway submarket that is expected to be sold to an institutional user which would have required significant capital to complete and lease, (ii) $135.3 million related to four non-Megacampus vacant office properties in our Palo Alto submarket that would have required significant capital investment to convert to laboratory use, (iii) $79.2 million related to six non-Megacampus operating properties in our San Carlos submarket that would have required significant capital investment to convert to laboratory use, (iv) $50.4 million related to a land parcel located outside of a Megacampus aggregating 344,000 SF in our Austin submarket, and (v) $41.6 million related to one future development project in our Palo Alto submarket that, due to the project’s financial outlook, would have required significant capital to complete the development and lease the properties. |
|
(2) |
Calculated in accordance with standards established by the Nareit Board of Governors. |
|
(3) |
Primarily relates to one non-real estate investment in a privately held entity that does not report NAV. |
The following table presents a reconciliation of net income (loss) per share attributable to Alexandria’s common stockholders, the most directly comparable financial measure presented in accordance with GAAP, including our share of amounts from consolidated and unconsolidated real estate joint ventures, to funds from operations per share attributable to Alexandria’s common stockholders – diluted, and funds from operations per share attributable to Alexandria’s common stockholders – diluted, as adjusted, for the periods below. Per share amounts may not add due to rounding.
|
Three Months Ended |
Nine Months Ended |
|||||||||||||
|
9/30/26 |
6/30/26 |
3/31/26 |
12/31/25 |
9/30/25 |
9/30/26 |
9/30/25 |
||||||||
|
Net (loss) income per share attributable to Alexandria’s common stockholders – diluted |
$ (3.74) |
$ (0.43) |
$ 2.10 |
$ (6.35) |
$ (1.38) |
$ (2.06) |
$ (2.09) |
|||||||
|
Depreciation and amortization of real estate assets |
1.58 |
1.59 |
1.61 |
1.65 |
1.73 |
4.77 |
5.34 |
|||||||
|
Gain on sales of real estate |
— |
— |
— |
(1.80) |
(0.06) |
— |
(0.14) |
|||||||
|
Impairment of real estate – rental properties and land |
3.74 |
1.30 |
0.03 |
8.45 |
1.90 |
5.07 |
2.67 |
|||||||
|
Allocation to unvested restricted stock awards |
(0.01) |
(0.02) |
(0.01) |
(0.02) |
(0.01) |
(0.04) |
(0.02) |
|||||||
|
Funds from operations per share attributable to Alexandria’s common stockholders – |
1.57 |
2.44 |
3.73 |
1.93 |
2.18 |
7.74 |
5.76 |
|||||||
|
Unrealized (gains) losses on non-real estate investments |
(0.13) |
(0.77) |
0.06 |
(0.58) |
(0.11) |
(0.84) |
0.42 |
|||||||
|
Significant realized losses on non-real estate investments |
— |
— |
— |
0.61 |
— |
— |
— |
|||||||
|
Impairment of non-real estate investments |
0.08 |
0.05 |
0.07 |
0.12 |
0.15 |
0.20 |
0.45 |
|||||||
|
Impairment of real estate |
— |
— |
— |
0.07 |
— |
— |
0.23 |
|||||||
|
Loss (gain) on early extinguishment of debt |
0.02 |
— |
(2.14) |
— |
— |
(2.12) |
— |
|||||||
|
Acceleration of stock compensation expense due to executive officer resignation |
— |
— |
— |
0.01 |
— |
— |
— |
|||||||
|
Allocation to unvested restricted stock awards |
— |
0.01 |
0.01 |
— |
— |
0.02 |
(0.01) |
|||||||
|
Funds from operations per share attributable to Alexandria’s common stockholders – |
$ 1.54 |
$ 1.73 |
$ 1.73 |
$ 2.16 |
$ 2.22 |
$ 5.00 |
$ 6.85 |
|||||||
|
Weighted-average shares of common stock outstanding – diluted |
||||||||||||||
|
Earnings per share – diluted |
170,751 |
170,718 |
170,867 |
170,394 |
170,181 |
170,689 |
170,278 |
|||||||
|
Funds from operations – diluted, per share |
171,418 |
171,210 |
170,867 |
170,504 |
170,305 |
171,169 |
170,351 |
|||||||
|
Funds from operations – diluted, as adjusted, per share |
171,418 |
171,210 |
170,867 |
170,504 |
170,305 |
171,169 |
170,351 |
|||||||
Refer to “Definitions and reconciliations” in the Supplemental Information for additional details.
 View original content to download multimedia:https://www.prnewswire.com/news-releases/alexandria-real-estate-equities-inc-reports-3q26-and-ytd-3q26-net-loss-per-share–diluted-of-3-74-and-2-06–respectively-and-3q26-and-ytd-3q26-ffo-per-share–diluted-as-adjusted-of-1-54-and-5-00–respectively-302919655.html
SOURCE Alexandria Real Estate Equities, Inc.
